

Deductible, Copay, Coinsurance & Out-of-Pocket Maximum: What Do They Mean?

Updated: Sep 22
When you're comparing health insurance plans, you’ll probably run into four terms over and over again: Deductible. Copay. Coinsurance. Out-of-pocket maximum. They sound similar, and it's easy to get them mixed up, but they each play a different role in determining how much you pay for healthcare.
Understanding these four terms can make comparing health insurance plans much easier and help you avoid choosing a plan based solely on its monthly premium.
What is the Deductible?
Your deductible is the amount you typically pay for covered medical services before your insurance company begins sharing the cost. Until you reach that amount, you may be responsible for the full cost of many services unless there is a stated benefit, such as a set copay for a doctor visit.
For example, suppose your plan has a $5,000 deductible. If you slipped in the kitchen and broke your wrist, costs like X-rays, imaging, or surgery could be your responsibility until you reach that $5,000 deductible. After that, your insurance would begin sharing the cost of additional covered medical bills based on your plan, typically through coinsurance, until you reach your out-of-pocket maximum.
Deductibles and monthly premiums often work in opposite directions. Plans with lower monthly premiums tend to have higher deductibles, while plans with lower deductibles generally cost more each month. If you don't expect to need surgery or other expensive medical care, saving each month with a higher deductible plan may be attractive. On the other hand, if you know you have an expensive procedure coming up, paying a higher monthly premium for a lower deductible could potentially save you money overall.
What is a Copay?
A copay, or copayment, is a set dollar amount you pay for a covered healthcare service.
For example, a plan might have a $30 copay for a doctor visit, a $50 copay for an urgent care visit, and different copays for prescription medications.
The exact amounts and services covered by a copay vary by plan. One advantage of a copay is predictability: knowing in advance that your portion is a specific dollar amount. But don't assume every doctor visit or service automatically has a copay. The plan's details determine how the service is covered.
What is Coinsurance?
Coinsurance is different from a copay because it's usually expressed as a percentage rather than a fixed dollar amount. It often comes into play after you've met your deductible.
Let's say for example you get a $1,000 procedure done and your plan has 20% coinsurance. Your share of the cost would be $200, while the insurance would cover $800. This cost sharing would typically continue until you reach what is called your max-out-of-pocket.
This is why coinsurance deserves attention when comparing plans. That same $1,000 procedure could cost you double if your coinsurance was 60/40. A plan with a low monthly premium might look attractive at first, but if you need significant medical care, the percentage you are responsible for can become important.
What is an Out-of-Pocket Maximum?
The out-of-pocket maximum represents the most you would generally have to pay during a plan year for covered in-network services. Once you reach the applicable out-of-pocket maximum, the plan generally pays 100% of covered in-network benefits for the remainder of the plan year.
Premiums generally don't count toward the out-of-pocket maximum, and costs for services the plan doesn't cover—or care received outside the applicable network—may not count either. That's why you should never look at the out-of-pocket maximum without also looking at the plan's network and coverage rules.
How These Four Terms Work Together
Here's a simple way to think about them:
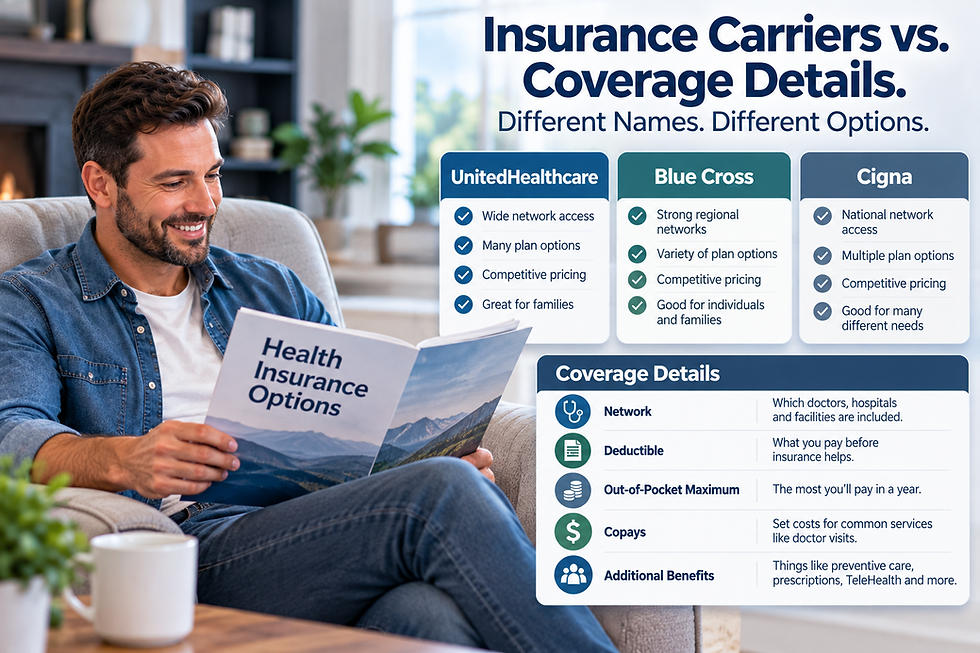
Deductible: What you may have to pay before the plan begins sharing certain costs.
Copay: A fixed dollar amount you pay for a covered service.
Coinsurance: A percentage of the cost you pay for a covered service.
Out-of-pocket maximum: The limit on your covered cost-sharing for the plan year, subject to the plan's terms.
These aren't necessarily separate charges that happen one after another. A plan can use different combinations of deductibles, copays and coinsurance for different services.
Don't Choose a Plan by Premium Alone
A lower-premium plan might have a higher deductible and higher potential out-of-pocket costs when you need care. Another plan might cost more each month but cost less overall if you need major medical services. Neither is automatically the better choice. It depends on your budget, healthcare needs, providers and how much financial exposure you're comfortable taking on.
The Bottom Line
You don't need to memorize every insurance term to make a good decision. Start with these four; Deductible, Copay, Coinsurance, Out-of-pocket maximum.
Once you understand these numbers, comparing health insurance plans becomes much less intimidating. If you're comparing coverage for yourself or your family and aren't sure how the numbers fit together, we're happy to help you compare the overall plan design, not just the monthly premium.
Comments